Thirsty for information about Alaska Real Estate? Whether you're a home buyer, seller, investor, or just curious, we've got you covered! Comments and questions are welcomed!

April 19, 2016

Yearly Home Maintenance In Alaska

Yearly Home Maintenance in Alaska

If you're a fellow homeowner, investment property owner or property manager, you probably know all about unexpected expenses in regards to property maintenance. In this blog, let's look at a short list of some simple things we should be doing yearly to keep deferred maintenance a thing of the past.


Roof Maintenance
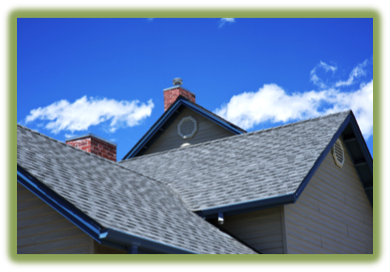
picture of home roofMost Alaskan homes are asphalt composition shingle roof. Mixed with out many trees of various genus’s, especially birch trees with floating leaves, we tend to collect a good portion of falls short-lived foliage on our roofs. It's important to clean them yearly at the end of fall, paying close attention to moss build up. Also remember, it is better to gently scrape asphalt shingle (if there is gunk build up) than it is to pressure wash, as pressure washing will greatly deteriorate the lifespan of your shingles.

Also, let’s not forget about our roofs in the wintertime. Did it snow more than 12 inches in 24 hours? Or is it really heavy, wet snow? SHOVEL IT! Or pay someone to shovel it. Trust us on this one.


Gutter Maintenance

Yes, this is a separate section of maintenance from the roof. Make sure your gutters are scraped clean and free from any blockage, preferably at the start of the first snow. By Anchorage's first snow, most leaves should have fallen and you're clear to clean them for the winter.


Heating System Inspection
murphys law house furnaceEvery landlord will tell you, heating and plumbing issues are the worst. They often arise when it's most inconvenience and bring the highest cost to homeowners for repairs. Avoid this slippery slope by getting your heating system and boiler inspected every year by a trusted heating or mechanical company. Inspections are relatively cheap, and help establish a working relationship with a company or handy man that knows your system.


Grounds Maintenance
don't do this to your alaska homeProbably one of the least fun things on the list - pick up your garbage. I prefer to do this twice a year at least. One at the end of break-up (when the snow and ice first melts), then again right before the first snow. This will help keep your property pristine giving it that curb appeal that gives you pride of ownership in your home. If you skip out on this step, especially before winter, your spring will look like a dumping ground for all of Anchorage!


Crawl Space

Once a year, it's important to inspect your crawl space. Yes, you'll have to brave yourself against claustrophobia and arachnophobia. Don't worry though, inspection of crawl spaces rarely leads to a paramount of a JRR Tolkien book - you'll be fine! Look for random leaks, foundational issues, drainage issues on the exterior of the building and possible infestations. Brave going down into the crawl space once a year and you'll be glad you did!


Exterior maintenance
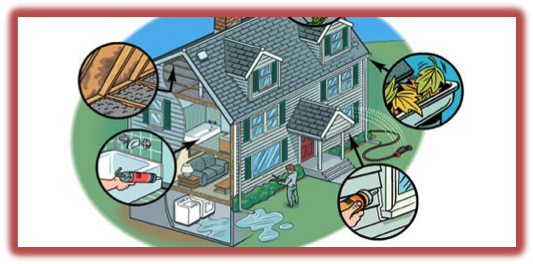
anchorage home exterior maintenance infographicUnless you're doing a major overhaul, there isn't much to exterior maintenance. Look for loose siding, chipping paint and small imperfections to your buildings' exterior that could worsen over time. Take care of what you can with well-done cover jobs, and hire it out if you can't do it well. I've seen loose side boards lead to wood rot that cost a lot of money to fix. Don't let a small exterior issue turn into a contractor’s gold mine.


There you have it! Follow these easy steps to secure and maintain your building for the best long-term results. I'm a huge fan of the saying, "Pay today, or pay tomorrow."


Now you know what you should be doing, turn your "shoulds" into "musts" and you'll avoid big headaches later in your properties life.


For more informations, or if you have questions about Real Esate in Anchorage, Alaska, please contact our local Realtor James Cash at (907)-360-7448 or e-mail at jamesfcash@gmail.com

Posted in Education, How To
April 17, 2016

Why A Fourplex Could Be Your Best Investment

Why A Fourplex Could Be Your Best Investment

Investment anchorage real estate fourplex investing


            In this day and age, there is always speculation what is the best investment. On one side of the coin, wall street is telling us that diversification of our portfolio over many blue chip stocks is our best bet. The government tells us investing in treasury bonds is a sure way to beat inflation and a safeguard for our money. Then there are realtors like myself who are advocating for investing in real estate. But who’s right?


            The truth is, all of us. Depending on your financial goals and the amount of assumed risk you want to carry, any one of these options could be great for you. Personally, I got tired of riding the stock waves years ago and cashed out on the upswing by sheer luck. Many of us were not so lucky. I entered the Anchorage Real Estate market not to purchase my first home, but to invest.


            Following Robert Kiyosaki’s (author of Rich Dad Poor Dad) model of the “Wealth Building Phase,” I knew that working my corporate job I had to be highly leveraged just starting out in order to create some sort of financial future for myself. I was hard pressed just to save any sum of money every month after my bills were paid. At that time, I lucked into investing because I heard some older gentleman tell me to, “Buy a fourplex and live in it until you’re tired of it, then buy another one.”


            I didn’t know that his words carried such wisdom. He was a man I respected and knew he had done well for himself. He was by no means the next Donald Trump or Warren Buffet, but he was not a poor man by any stretch of the imagination. In that one sentence, he ignited my passion in real estate and my mindset shifted. Those words changed my life.


Why Is Investing In A Fourplex So Great?


Rent Free

            Aside from being the king or queen of the quarters (if you have a coin-op laundry, you get to collect a kings ransom in arcade funding every month), it enables you to live very cheap. You get to rent out 75% of the units, and can even live rent-free while some one else pays your mortgage. Even if you’re not living entirely rent free, you’re monthly payment to live in a roof-covered-sleeping-place is very low. This enables you to save your money, or pour it back into your investment.


Highly Leveraged

            For an FHA loan, you only have to put 3.5% down to get into that property (VA loan – Veterans/Military – is 0%). That’s crazy! In 30 years, you could control half a million dollars in Real Estate by putting down only $17,500! Ok – things will eventually go wrong and you’ll have to put more capital into the building so it doesn’t fall apart, but a man can dream! Even with capital expenses and regular upkeep, your investment and ROI (return on investment) is insane. Not to mention, in 30 years, your building will most likely inflate beyond the initial purchase price.

Inflation or Deflation – Who Cares?

            When you invest in treasure bonds, or even stocks for that matter, it can be a race against inflation. With the unregulated printing of U.S. Dollars by the federal reserve, exacerbated by the greed of the government to deficit spend, inflation is a very real threat against protecting your assets. Being so HIGHLY leveraged, you really don’t have to care about inflation, or even deflation for that matter – or a combination of both.  I like to use the following example:


Lets say the U.S. Dollar is worth $1 (One Dollar).


You Purchase a home for $100,000. You buy it with an FHA loan, at 3.5% down, investing only $3,500.


Printing U.S. Dollars unregulated inflates the actual cost of goods and commodities, therefor prices of everything goes up, even your home.


Due to this, your home is now worth $200,000 in 30 years.


The Actual Value of a U.S. Dollar is now worth $0.50 (50 Cents). This is because inflation of prices deflated the value of the dollar. Example: They say an ounce of gold has always bought a nice mens’ designer suite. In 1930 that may have been $20 – the price of an ounce of gold. Today, it may cost around $1,300. Prices of goods have inflated, and the true value of a dollar has gone down (deflated).


The Actual Relative Value of your home, in comparison with when you bought it, is $50,000. (Sad I know).


You only spent $3,500 and have made it grow by 1,423%. You’ve managed to leverage your money, and even in the worst conditions of economic management by our governing bodies, you beat the system. Congratulations!


A Roofed Stepping Stone

            I tell people live like you are still renting when you move out of your fourplex, and don’t take any income from it. Pretend it’s not there – it’s your magical investment in a far away place where you can’t harm it’s money making potential!

            Some day, when you decide you want to move into other endeavors, opening your own business, or getting into more Real Estate investing, you have a little nest egg you can leverage. Take out a HELOC (Home Equity Line Of Credit) to play around with, or sell it and 1031 Tax Exchange into a bigger, better cash-flowing commercial property. The possibilities are really endless.

P.S. You could also buy a fourplex when your kid is 1-5 years old and tuck it away so it pays for their college, and they have a place to stay when they graduate and decide not to work!


Tax Benefits

            The tax benefits of home ownership are real. The tax benefits of owning a fourplex are even more real! Interest, depreciation, repairs, legal and professional services just to name a few! I don’t claim to be a CPA, so don’t ask me the specifics here. Ask your accountant about all the amazing things your fourplex can tax shield you from!


These are not all of the amazing things a fourplex can do for you, just scratching the surface. Don’t think you only have to go big. Start with a duplex if that’s your comfort level (though they don’t cash flow as well and are a quasi-investment). Don’t take my word for it, just do some research of your own and you’ll soon see the benefits.


For more information about fourplexes, investment properties, multifamily properties or Real Estate in Alaska, contact our local expert James Cash at (907)-360-7448 or jamesfcash@gmail.com


April 7, 2016

How To Raise Your Credit Score For A Home Loan

How To Raise Your Credit Score For A Home Loan


If you've ever been denied for a home loan, or dream of owning your own home but can’t due to lower credit, I can sympathize with you. Rest assured, there is hope! In this blog post we will go over the best and fastest ways to raise your credit to an acceptable level to obtain your very first home loan!


If you haven't read our blog post yet on "What is my credit score?" click here to take a look. 


            THE BASIC WAYS TO RAISE YOUR CREDIT FAST

Briefly, these are a few ways to increase your credit quickly, and dramatically. We will cover these in depth:

·      PAY OFF COLLECTIONS

·      BRING ACCOUNTS CURRENT

·      GET A SECURED CREDIT CARD

·      LOWER DTI

·      CONSOLIDATE DEBT

·      OPEN REVOLVING ACCOUNTS IF NONE EXIST

Before you begin, you should obtain a copy of your credit report.


PAY OFF COLLECTIONS

        If you have not paid a company, medical bill, credit cards, or stopped paying a revolving debt, you might have a collection. Follow these easy steps to take control and wipe these collections off of your account. 

1.) Review a copy of your credit report

2.) Work with the companies directly and not the collections company. Again, do not work with the collection agency! Why? After you pay a collections company, they will not remove this from your credit report for seven years (unless it was proven to be fraudulent).

3.) Make sure each companies puts it in writing they will remove this account from showing up on your credit report and ask the collection company to remove it from their file. 


BRING ACCOUNTS CURRENT

If you have any late accounts open, bring them current immediately or contact the company to have them assist you in your late payments. You may be able to set up a payment plan without reporting you to a collection agency or credit bureau. You will be surprised how many companies will work with you if you tell them your situation. 


GET A SECURED CREDIT CARD

A secured credit card works like a normal credit card, except you have to put the money down up front. For example, if you give your bank $500, they will give you a $500 secured credit card. After a year of using this, paying on time and not keeping the card maxed out; they will normally refund you the $500 and increase your credit limit. Pro Tip: leave the balance on this card very low - this will help push your credit limit and credit score higher. 


LOWER DTI (DEBT TO INCOME)

If you have a lot of revolving debt, like credit cards, lines of credit or car loans, pay them down! After you've run your credit report, you can see where your DTI is. Typically under 35% will yield an ideal credit score. Pro Tip - don't push this too low, as credit bureaus like to see a prospective client using credit responsibly. 


CONSOLIDATE DEBT

If you have high interest credit cards or student loans, you can consolidate debt into one place. Typically these are shown as a personal line of credit (revolving account) and may have a lower interest rate. I've had clients open these and consolidate their debt and see immediate increases to their credit score.


OPEN REVOLVING ACCOUNTS – If You Don’t Have Any Yet

If you don't have any revolving accounts, like credit cards, lines of credit or a car loan, your credit score may be low because there is no history. Open a secured card, or try to open a normal credit card. The new revolving accounts and available credit will help boost your score. Be careful not to open any of these too close to applying for a loan as this could be an issue for mortgage lending companies.


There's a lot of moving pieces here, but if you follow this guide and the steps within, you'll most likely be within 6 months of obtaining a home loan. 


P. S. If you're struggling to come up with the money to pay down debt, consider working a second job. If you're committed to buying a home, you may have to make some initial sacrifices! 

Posted in Education, How To
March 22, 2016

Monopoly - Real Estate Lessons

            I was playing monopoly this weekend – you know, the old-fashioned board game with paper money, iconic pewter playing pieces and nostalgia of childhood epic-fun and crushed dreams.

            The first game, I was playing very conservatively. If the property didn’t fit my exact needs and wants, I didn’t buy it. I figured, “Ehh, I’ll wait a round and after passing go, when I have some extra spending money, I’ll snatch it up.” I was saving my money and opportunity to land on Park Place and Board Walk, the Holy Grail of monopoly real estate.

            Wouldn’t you know it, after a few strolls through the block, I was able to control the most valuable real estate. Now it was time to amass my empire and erect new construction houses, and develop some hotels. Just as my world was reaching new levels of economic development, something else was taking place I didn’t realize.

            My wife had complete control of a good majority of the board. Over half of the first portion of the board was now covered with one or two houses – later I would come to call this portion of the board, “Death Row.” Her tactic was buying anything and everything she could afford. She was making any opportunity afforded to her work.

            I was able to dodge some of her properties, luckily landing on “Chance” and “Community Chest.” After a while, she landed on Board Walk. I felt pretty proud to be collecting $500+ in rent, and felt the start of my reign as The Monopolist.

            Soon after collecting my biggest rent check, I started to feel the slow bleed of her single and double-housed properties. The same low-end properties, which I scoffed at, were now getting the best of my checkbook. Almost overnight, I began to barely scrape by, having to mortgage everything I owned. Suddenly my empire began to crumble, and hers began to rise. Her “Death Row” was now laden with hotels and my only hope was to go to jail, AKA sit in the corner and hope the world would suddenly change for the better.

            Needless to say, I lost my houses on the most prestigious properties, and was out of the game quickly. I lost it all. This taught me some very valuable lessons about real estate.


            Firstly, when you start out in the real estate game, it’s all about wealth building. Its like Robert Kiyosaki says in part of his strategies (Author of Rich Dad Poor Dad), there’s a time to manage wealth, and then there’s a time to build it. When you’re just starting out, you should be trying to control as much real estate as possible. This, at times, means you might need to be highly leveraged.

            Secondly, you should diversify your real estate portfolio. I’m not saying branch out into stocks and bonds, but spread it evenly between property types. Don’t only invest in high-end properties that fit your specific criteria. This will not make you bullet proof. To those of you who say diversify across all platforms, take a lesson from Warren Buffet who said, “Diversification is the lack of knowledge.”

            Thirdly, don’t let the state of the economy dictate your actions. If you are at a point in your life where it makes sense to build wealth, build it. Do not wait on the sidelines at hopes the world around you will change – make it change. There are always opportunities out there, you just have to keep an eye out and be persistent. Think of it like the people who want to lose weight, and wait for Monday to come to start their diet. Mondays never come!


            After licking my wounds, we played a second game. This time, my strategies shifted. I began to barely scrape by in the beginning, while picking up as many pieces of property as possible. This time, I was building my wealth and I was very highly leveraged.

            No longer did I have specific criteria of property, I just bought it if it made sense. The game went much differently this time. My wife, who already implored an awesome strategy, was battling with me for control. After a little bit of luck, and some application of my knowledge, I was able to dominate the board, all without the two properties I had coveted so highly before. Before long, I was able to exact revenge and relive my gloating seven-year-old-self as the Monopolist.


            Monopoly also taught me some other valuable nuggets of real estate wisdom, but that’s for another time!


For information about Real Estate in Alaska, contact our local Real Estate Expert James Cash at (907)-360-7448 or e-mail at jamesfcash@gmail.com

Posted in Education
March 15, 2016

Anchorage Real Estate Supply and Demand

Anchorage Real Estate Economy

Supply and Demand


            It’s really Econ. 101, Supply and Demand. It sounds pretty straight forward, but what are the factors that surround this? Let’s take a closer look to extrapolate whether or not we can forecast the future.

            Firstly, let’s identify a few exogenous determinants of real estate demand:

·      Market Size (Population and Employment)

·      Income/Wealth

·      Prices of Substitutes

·      Expectations

Market Size

            Two of the biggest factors that drive market size are population and employment. For instance, the bigger the population, obviously the more land and livable dwellings needed. If this shrinks, just the inverse will happen. Secondly, employment or output will be the second major factor in market size worth mentioning. If unemployment rises dramatically, more homeowners will be in higher rates of default, pushing them out of their houses and into the rental market.

Income / Wealth

            In relation to residential real estate, average GDP, or income will affect the price of homes in relation to goods being kept at a constant price. In laymans terms, if the cost of goods (utilities, groceries, gas, ect.) remain the same, while the income of the average person rises, they will have more available money. In a market with limited amount of homes, land and new construction (Anchorage for instance), average price per square foot of dwelling residence will go up, i.e. the cost of homes will rise in accordance with this. Conversely, if the average GDP of consumers falls, we can expect that the average price per square foot in the residential sector will also fall in a scalable manner.

Price of Substitutes

            In a market with limited available land, substitutes for homeownership often become higher – enter the rental market. Currently, rental prices in Anchorage are at a high. This makes the residential sector also have a higher shift. If substitutes (rents/rentals) are high, this makes owning a home more desirable, thus putting more demand on affordable homes, making inventory scarce and prices high.

Consumer Expectations

            Believe it or not, but in a closed market, consumer expectations can play a major role in the economy. For example, if it were widely thought that the price of gold or copper will go up due to a downshift in mining production (inventory), the price may rise and even effect other goods such as consumer electronics. If time comes to pass and production does not take a downturn, consumers will have paid a premium due to expectations that did not actually come to fruition.


Actuality of These Items


            If anyone tells you the end is coming, you might not want to believe him or her. No economist has a crystal ball, and people as a whole scarcely, accurately predict shifts in the economy.

            What we do know is that according to the Anchorage Bureau of Labor Statistics, last accurate data we can confirm is that the Anchorage unemployment rate is 5.3% (April 2015). Our population currently boasts just north of 300,000 people. In January of this year, according to the Department of Labor and workforce Development, there are 153,600 residents in anchorage with nonfarm employment (January 2016). Although data.ocala.com suggests there are 197,990 total in the workforce.

            During the great depression in the U.S., the unemployment rate as high as 25%. For us to see unemployment rates that high, we would have to lose around 40,000 jobs…that are a lot.

            We also have a buffer as an economy. If jobs are lost quickly, we can probably see the substitute market decrease, acting as a shield in the real estate economy. This will soften the prices of the residential real estate market, and increase inventory. It is worth noting that inventory, currently, is relatively low compare to a “healthy” market.


What We Do Know

            What we do know is that gas and oil is a commodity with limited availability, it will run out. Also we can see that employment from oil and gas impact state funding more greatly than it does consumer spending within the state (http://live.laborstats.alaska.gov/ces/ces.cfm?at=04&a=000020&adj=0#y2001).

            Land in Anchorage will always be scarce. There is just not much more buildable land that is available. This means that the population would have to leave in droves, tens of thousands of people at a time, for us to see a sizeable recession. If that is the case, it will be a momentary shift in the economy (in the grand scale of things). If this does happen, it will be time to buy for sure.


Wise Words From a Friend

            I had a friend tell me that they investing in the residential real estate market in San Francisco in the early 90’s. His home appreciated almost $30,000 in three years, from $165,000 to $195,000. He thought he had hit the height of the market, and there was talk of another collapse. He sold his home quickly in a hot market and thought to be the wiser.

            Today, if he still had his home, he told me it would have been worth over $500,000. He thought for sure the shift was coming (as many people had told him).

            The advice I give people is, make educated decisions based on your current condition. If it is a good move for you to sell today, sell today. If it is a smart move for your family to buy today, buy today. The mantra of, “We’ll see what the future brings” is that of some one who sits on the sidelines. To invest in your future, you must be proactive and not reactive.


- James Cash 

March 10, 2016

Cook Inlet Lending Center - Down Payment Assistance Program

Cook Inlet Lending Center

Down Payment Assistance Program (DPA)

Updated February 17th 2017 

            If you’re looking to buy a home in Anchorage, Eagle River, Wasilla and Palmer, this program may be for you. If you’re tired of renting your home, apartment or condo and not getting any return on that investment, you stand alongside a lot of other home buying hopefuls. What is one of the biggest hurdles to jump when buying a home? A down payment. The Cook Inlet Lending Center (CILC) is a new program offered for the Municipality of Anchorage, Mat-Su Borough and the Kenai Peninsula Borough.


Who is eligible?

The CILC is targeting individuals and families with low to moderate income with this down payment assistance program. You must be a part of the aforementioned Alaska boroughs. For more information about the program pertaining to income limits, please see the household size and maximum income limit below.


How it works

            The CILC down payment assistance program is basically a second mortgage for 20% of the loan, financed at 4% over 30 years. 4% is a ridiculously low interest rate that is fixed over the life of the loan! Borrowers will pay Cook Inlet Lending Center monthly for principal and interest, just like your typical loan. For full information and criteria please e-mail inquiries to jamesfcash@gmail.com, subject CILC Lending Program.


You should act NOW

            This down payment assistance program is limited on its funds, and is basically a first come first serve basis. At some point in the year, their funds will run out and could potentially be indefinitely postponed. Last year (2016) funding ran out by August. If you to take the time to get pre-qualified, they do guarantee your funds even if you do not close on your property until later in the year, so act now!


Overview

            This is a great down payment assistance program for Alaskans, specifically targeting Anchorage, Mat-Su Valley and Kenai. The Cook Inlet Lending Center program will allow first time home buyers without the money for a down payment, that show lending responsibility the power to get into the house of their dreams.


To start browsing at Anchorage homes, click here!

To start browsing Mat-Su homes, click here!


For more information about real estate in Anchorage, Eagle River and The Mat-Su Valley, contact our local expert James Cash at (907)-360-7448.

Feb. 29, 2016

2016 Palmer Alaska Real Estate Statistics

2016 Palmer Alaska Real Estate Statistics

February 29th, 2016


Below are the residential real estate sales statistics for Palmer, Alaska.


What we can draw from these statistics in Palmer is that the market is moving a long nicely. 


We can see that the inventory supply is very low. The closer we get to 6 months of inventory in any market tells it's a relatively healthy market for both buyers and sellers. This means that properties may tend to favor the seller in this market, since there is such a short supply for buyers to pick from. It could be time to sell in Palmer!

James Cash

Properties of Alaska

907-360-7448

Feb. 29, 2016

2016 Wasilla Alaska Real Estate Statistics

2016 Wasilla Alaska Real Estate Statistics

February 29th, 2016


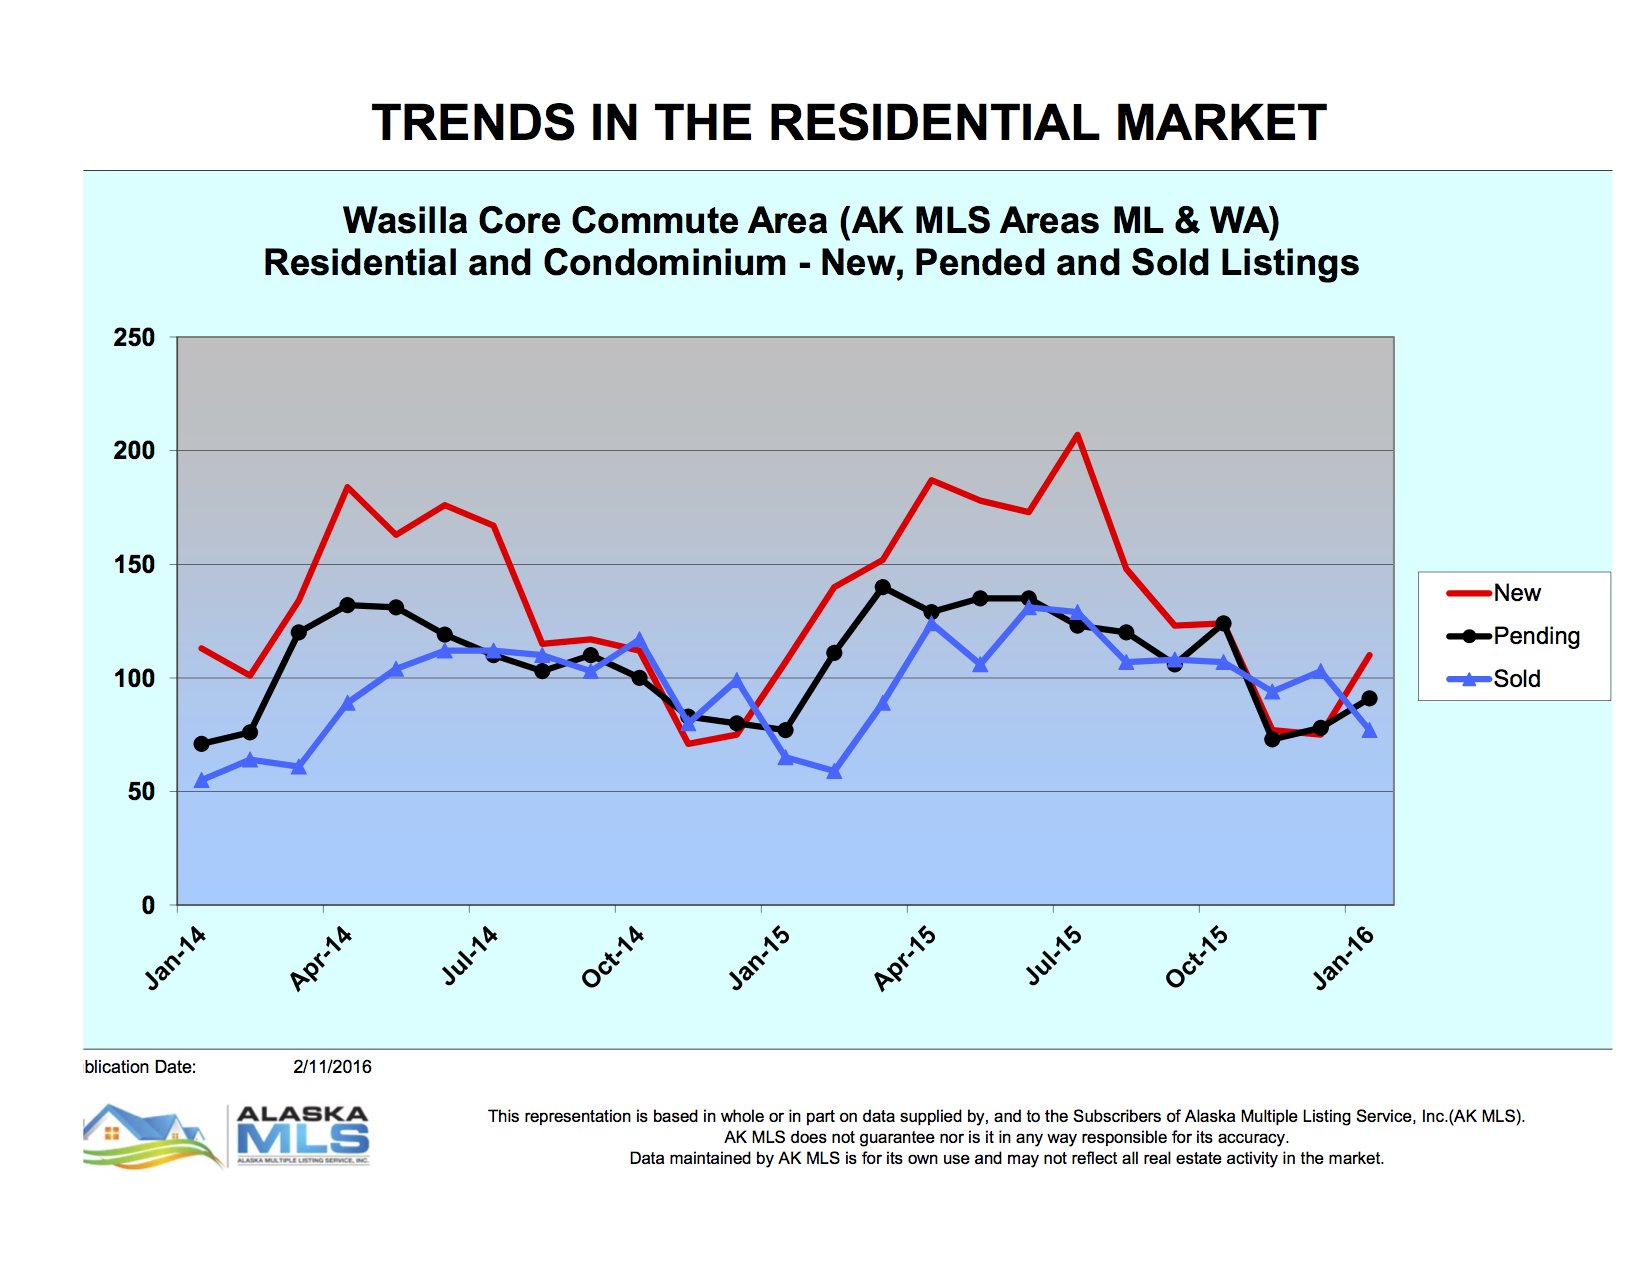
Below are the residential real estate sales statistics for Wasilla, Alaska.


What we can draw from these statistics in Wasilla is that the market is moving a long nicely. 


We can see that the inventory supply is a bit heavier than Anchorage, which is a good thing. The closer we get to 6 months of inventory in any market tells it's a relatively healthy market for both buyers and sellers.

James Cash

Properties of Alaska

907-360-7448

Feb. 23, 2016

Bank of America's New 3% Down Loan Program

Bank of America's New 3% Down Loan Program

Bank of America recently launched a new loan program that offers only 3% down to first time home buyers. The difference between this home loan and other moderately low down payment programs is that there is no private mortgage insurance (PMI). This could save borrowers thousands of dollars of the life-span of their loan, there are a few caveats though:


  • 660 Fico Credit Score
  • Cannot make more than median income in area
  • Must be borrower's primary residence
  • First time home buyers must take an education class

Although this loan program sounds more appealing than most other programs out there, don't rush to Bank of America just yet. The PMI is offset due to a higher interest rate over the life of the loan or a big upfront one time fee. This could also create some problems for investment companies and home owners alike. Since there is no mortgage insurance, tax payers will most likely have to take the hit due to defaulting home owners. Also, the same home owner will own less equity in their house at first, making higher payments and resale more difficult for them in the interim.


For more information on Anchorage, Eagle River and Wasilla real estate markets, contact our local expert James Cash at (907)-360-7448


Feb. 20, 2016

February News Letter